Moving to the Eastside from the Bay Area: What It Really Costs
If you're weighing a move from the Bay Area to the Eastside, the first question is usually the same: what does it actually cost? Not the headline price of a house, but the whole picture, including the monthly payment, property tax, insurance, and the day-to-day. I pulled fresh numbers this week so you can see where the real differences are, and where they aren't. This is general information, not tax, legal, or financial advice.
Are people really making this move?
Yes, and it shows up in the data. In Redfin's fourth-quarter 2025 migration report, the San Jose–San Francisco area had a net outflow of 21,230 Redfin users looking to move, and Seattle was the top out-of-state destination for people searching from the Bay Area. Keep in mind that's search behavior, not completed moves, and it covers the broader Seattle metro. Seattle also showed a net outflow of its own in that report, so it's a two-way street. The takeaway: you're not the first to run these numbers.
Home prices: the biggest line item
Here are the most recent figures I could verify:
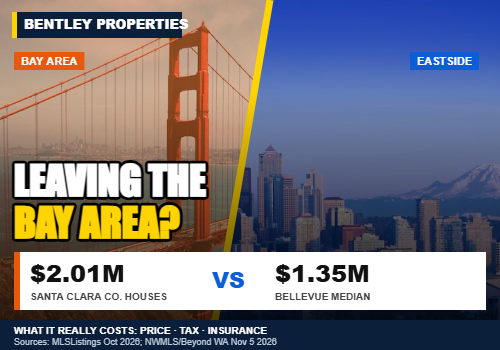
- Bellevue: $1,349,000 median sale price over the last 90 days (NWMLS data via Beyond WA, updated November 5, 2026), down 12.7% from a year earlier.
- Kirkland: $1,207,500 on the same basis.
- Redmond: $1,150,000 on the same basis.
- Santa Clara County, CA: $2,010,000 median for single-family homes in October 2026 (MLSListings), up 5.1% year over year. Attached homes (condos and townhomes) were $900,000.
- King County overall: $845,000 median in October 2026, with houses at $950,000 and condos and townhomes at $572,500 (Beyond WA).
A few cautions. The Eastside figures cover all property types in each city over 90 days, while the Santa Clara figure is single-family only, so it isn't a perfect side-by-side. Medians also move around with the mix of homes that happen to sell. But the direction is clear: a typical Eastside purchase can sit well below a Santa Clara County single-family purchase. How much depends on what you buy and where.
What that means for the monthly payment
Freddie Mac's survey put the average 30-year fixed rate at 7.18% as of November 5, 2026. Rates you're offered will vary with credit, down payment, and loan type, so treat the following as an illustration only. With 20% down at 7.18% over 30 years:
- A $1,349,000 purchase means a loan of about $1,079,200 and principal and interest of roughly $7,300 a month.
- A $2,010,000 purchase means a loan of about $1,608,000 and principal and interest of roughly $10,900 a month.
That's a difference of around $3,600 a month before taxes and insurance, and it's the single biggest driver of the comparison. It also explains why some buyers use equity from a Bay Area sale to put down a larger down payment here and lower the loan amount. Your lender can run exact numbers for your situation.
Property tax: different systems, not just different rates
This is where people get surprised, because the two states work differently.
California: Under Proposition 13, the base rate is 1%, and Santa Clara County totals generally run about 1.12% to 1.24% once local bonds are added (JVM Lending, updated October 2026). Annual increases in assessed value are capped at 2%, which is why long-time owners often pay far less than new buyers. When you buy, the assessment resets to your purchase price.
Washington: There's no Prop 13-style cap on assessed value. Your bill is based on the county's assessment, which is updated regularly, multiplied by a levy rate that varies by address. The City of Bellevue's website lists $7.10 per $1,000 of assessed value as the most common Bellevue rate for 2023, which is about 0.71%. The Tax Foundation lists an effective rate of about 0.75% for owner-occupied housing statewide. Your actual rate depends on the taxing districts at the specific address, and King County's Assessor publishes levy rate reports you can look up.
As an illustration only, 0.71% on $1,349,000 is roughly $9,600 a year. About 1.15% on $2,010,000 is roughly $23,100 a year. Those are estimates, not bills, and both depend on the specific property.
State income tax and other taxes
I verified this one: Washington does not levy an individual income tax on wages or salaries (Tax Foundation). That's a real difference from California, which does tax wages. But Washington isn't tax-free. The state sales tax rate is 6.5%, and the average combined state and local rate is about 9.51%. Washington also has a capital gains excise tax: 7% on long-term gains above a standard deduction ($278,000 for 2025), with a higher 9.9% rate on gains above $1 million beginning with tax year 2025. The Department of Revenue lists real estate among the exempt assets. There's also legislation on a separate tax on household income above $1 million that's slated for 2028, and the rules in this area are changing. Please talk with a CPA about your own situation, especially if you're selling stock, a business, or a home on the California side.
Homeowners insurance
NerdWallet's February 2026 data shows an average of about $1,520 a year in Washington for $300,000 of dwelling coverage. I didn't pull a comparable California figure, and insurance costs there have been shifting, so I won't guess. The practical advice: get quotes on both sides before you decide, using the actual replacement cost of the home you're considering. Premiums depend on the home's age, roof, and coverage choices.
Commute and day-to-day
I don't have a verified, current average commute figure to quote, so I won't invent one. What I can say is that the Eastside is a job center in its own right, with Bellevue, Redmond, and Kirkland all home to major employers and shopping districts. Your commute depends on where you work and what hours you travel. If you're heading to Seattle, a bridge or I-405 crossing is part of the equation, and tolls can apply on some routes, so test-drive the route at your actual commute time before you buy. Day-to-day costs like groceries, dining, childcare, and utilities vary by household. I'd rather you price your own habits than rely on an average that may not fit.
On lifestyle, Eastside buyers often point to parks and trails, waterfront access on Lake Washington and Lake Sammamish, walkable downtown cores in Bellevue and Kirkland, and a wide range of homes from condos to larger single-family houses.
A simple way to compare
Put the two homes side by side on one sheet: purchase price, down payment, monthly principal and interest, annual property tax, insurance quote, and commute. Then add the taxes that apply to your own income and any one-time moving and closing costs. If you're selling in California first, build in your net proceeds and the timing of the sale. The monthly savings are real for many buyers, but they're not the same for everyone, and a few line items can offset part of them.
Sources
Redfin Q4 2025 Migration Report; Beyond WA / NWMLS city pages (November 5, 2026); Beyond WA King County report (October 2026); MLSListings Santa Clara County (October 2026); Freddie Mac PMMS (November 5, 2026); JVM Lending Santa Clara property tax page (October 2026); City of Bellevue property tax page; Tax Foundation, Washington; Washington Department of Revenue, capital gains tax; NerdWallet Washington home insurance (February 2026).
If you're considering a move and want to talk through the numbers for specific Eastside areas, reach out anytime to set up a quick call.